Undeclared rent, put right. The Let Property Campaign, for UK landlords
HMRC’s Let Property Campaign is how you declare past rent: notify, then disclose and pay within 90 days. LetCompliance keeps every year’s rent and costs after it, on every paid plan from £7.99 a month for UK landlords.
No card to start.
Recognised by HMRC for Making Tax Digital on paid landlord plans. Ref. D3V9KL. See the GOV.UK listing (opens in a new tab)

Making the disclosure. How to make a Let Property Campaign disclosure
HMRC’s own steps, from its guide. LetCompliance helps with the first and keeps every year after the last.
Gather the figures
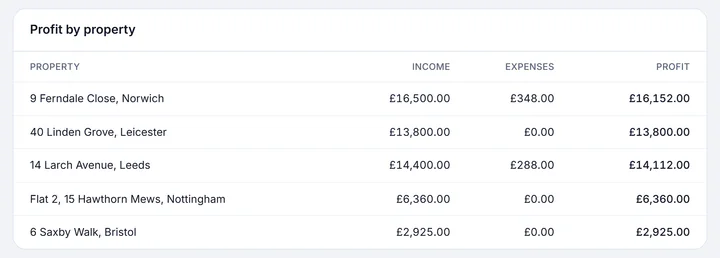
Rent received and allowable costs for each year you need to cover, property by property. Where records are missing, HMRC asks for your best estimate, with your workings kept.
Sample account with made-up details, 20 Oct 2026 Notify HMRC
Tell HMRC you will be making a disclosure through its online service, Tell HMRC about underpaid tax from previous years. You will need to sign in.
Work out what is owed
For each year, the tax due, the interest from the date it was due and the penalty for your behaviour.
Sample account with made-up details, 20 Oct 2026 Disclose and pay within 90 days
Send the disclosure and the payment together, by the date on HMRC’s acknowledgement. If you cannot pay in full, speak to HMRC before you send either.
Register for Self Assessment
If you are not registered, register now. This year’s income goes on your next tax return, not in the disclosure.


This is general information from HMRC’s guidance, not tax advice. LetCompliance does not make the disclosure or work out the penalty.
What keeping it right saves you. What keeping rental records right saves a landlord
5 tax years in the Tax pack, this one and the four before. Pick a tax year and the Tax pack fills in its SA105 boxes from that year’s entries, with the profit for each property, ready for a return or your accountant.
Before Wondering where the rent went
Now Rent you mark paid is posted as income on its date, against its property, so each tax year’s rent is counted as it arrives.
Before Losing the receipts
Now Photograph a receipt and its supplier, amount and date are read into a draft expense for you to check, in the tax return’s own categories.
Before Rebuilding a past year
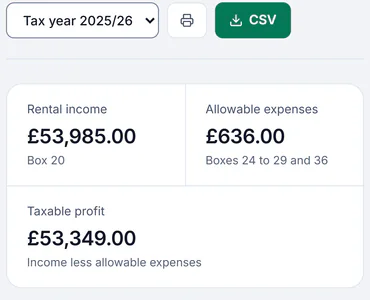
Now Pick 2025/26 and the boxes fill in from that year’s entries: £53,985 of rent, £636 of costs and £53,349 of taxable profit in the sample account, across its five properties.
Everything it does. Rental records after a Let Property Campaign disclosure, feature by feature
- Rent you mark paid posted as income on its date, against its property and tax year
- Rent collected by Direct Debit posted to the ledger and the year’s income by itself
- Receipts read from a photo into draft expenses, in the tax return’s own categories
- An entry added by hand, split across properties where a cost is shared
- Every entry on its property, with the receipt kept beside it
- The Tax pack in SA105 boxes for this tax year and the four before, on paid plans
- Profit for each property in each tax year
- An export for the year
- Making Tax Digital quarterly updates worked out from the same entries, on paid plans
- Whether Making Tax Digital starts for you, read from your own records
- A read-only link for your accountant to the SA105 figures, the ledger and the receipts, on every plan
The tax side of the let, kept as you go. How the tax side of the let is kept as you go
Rent and costs, by tax year
Every entry on its property and in HMRC’s categories, with the receipt kept beside it and an export for the year.
Making Tax Digital
The quarterly updates worked out from the same entries, checked by you and sent to HMRC, on paid plans.
Your accountant, read only
One link shows your accountant the SA105 figures, the ledger and the receipts for any tax year, with nothing they can change.
From £7.99 a month, with every tax year kept. Rental records for landlords on every paid plan
Finance and receipt reading come with the 3-day trial and every paid plan. The Tax pack with its SA105 figures and Making Tax Digital are on every paid plan, not the trial. Plans are priced by portfolio size, not per entry or per return.
Rather your accountant handled the disclosure? They can read the same figures, the ledger and the receipts through a read-only link, on every plan. How accountant access works
Let Property Campaign questions, answered. The Let Property Campaign: the timetable, the years and the penalties
Is the Let Property Campaign still open?
HMRC’s guide, last updated on 6 April 2026, gives no closing date (checked 20 October 2026). Check GOV.UK before you notify.
How many years of undeclared rental income do I need to disclose?
Up to 4 years where you took reasonable care, up to 6 where you were careless, and up to 20 where it was deliberate or you never registered for Self Assessment (Taxes Management Act 1970, sections 34 and 36). HMRC says it expects most people to pay for a maximum of 6 years. Years still due on a normal tax return go on that return instead.
What penalty will I pay?
It depends on why the income was not declared and whether you came forward before HMRC found it: from nothing where you took reasonable care, to up to 30% for careless, 70% for deliberate and 100% for deliberate and concealed, and up to 200% for offshore income. You work it out yourself in the disclosure. This is general information from HMRC’s guidance, not tax advice.
What if HMRC has already contacted me?
If HMRC has told you it is opening an enquiry or a compliance check, a campaign disclosure is unlikely to be accepted: tell the person running the enquiry instead. HMRC says a full and early disclosure still influences the penalty. It also says it cannot offer immunity from prosecution, though a complete, unprompted disclosure is an important factor when it decides whether to investigate criminally.
Can I pay in instalments?
HMRC expects the payment with the disclosure. If you cannot pay in full, its guide says not to submit the disclosure or the payment until you have spoken to HMRC.
Can LetCompliance make the disclosure for me?
No. The disclosure is made to HMRC through its online service, by you or an adviser. What LetCompliance does is keep the records from then on: rent and costs by property and tax year, the SA105 figures on paid plans, Making Tax Digital, and a read-only link for your accountant.
Is there a Let Property Campaign calculator?
HMRC’s guide links its own calculator for tax, interest and penalties, for straightforward cases. It asks you to work out each year’s tax first, to enter all the income for that year, and not to enter rental profits as profits from self-employment.
How long do I have to make a Let Property Campaign disclosure?
90 days from the date you receive HMRC’s acknowledgement of your notification. The payment is due by the same date, unless you have agreed payment terms with HMRC by then.
Can a couple make one disclosure together?
No. HMRC’s guide says one disclosure cannot include more than one person: where a husband and wife both have undisclosed income, each completes a separate disclosure showing their own share, and HMRC needs a separate notification for each.
Can a limited company use the Let Property Campaign?
No. It is for individual landlords. HMRC’s guide says it cannot be used to disclose on behalf of a company or a trust, or for non-residential property such as a shop, a garage or a lock-up.
Do I need to register for Self Assessment after a disclosure?
If you are not registered, HMRC says to register now. Income from the current tax year goes on a tax return, not in the disclosure, and a tax return HMRC sent you for any year from 2022 to 2023 onwards that is still outstanding is completed rather than included.
In depth. The Let Property Campaign in brief, and the records after it
The Let Property Campaign, in brief
Who it is for, the timetable, how far back it goes and what it can cost, each from HMRC’s guidance or the law behind it.
Who can use it
Individual landlords letting homes in the UK or abroad: one property or several, holiday lets, a room in your own home above the Rent a Room threshold and inherited property, and landlords who live abroad too. Not a company, a trust or non-residential property.
Notify first, then 90 days
Tell HMRC you will be making a disclosure through its online service. You then have 90 days from its acknowledgement to send the disclosure, with the tax, the interest and any penalty paid at the same time.
Sources: HMRC, Let Property Campaign: your guide to making a disclosure (updated 6 April 2026) (opens in a new tab) and GOV.UK, Tell HMRC about underpaid tax from previous years (opens in a new tab)
How far back it goes
Up to 4 years where you took reasonable care, 6 where you were careless, and 20 where it was deliberate or you never told HMRC about the income. HMRC says it expects most people to pay for a maximum of 6 years.
Sources: HMRC, Let Property Campaign: your guide to making a disclosure (updated 6 April 2026) (opens in a new tab) and Taxes Management Act 1970, section 36 (opens in a new tab)
Missing records
Where records are incomplete, HMRC asks for your best estimate of the income, and for your workings to be kept in case it asks how you reached it. Bank statements help.
Interest from the due date
Interest runs daily from the date the tax was due until it is paid, and a disclosure with the wrong interest can be rejected as incomplete.
If HMRC has been in touch
A campaign disclosure is unlikely to be accepted once HMRC has told you it is opening an enquiry or a check: tell the officer running it instead. HMRC cannot offer immunity from prosecution.
Proposed reporting by agents and deposit schemes
HMRC already sends letting agents and deposit schemes over 10,000 notices a year for rent data. A consultation open until 20 January 2027 proposes they report monthly or quarterly instead. It is a proposal, with no start date. What HMRC knows about your rental income has the detail.
Source: HMRC consultation, 28 October 2026 (opens in a new tab)
The penalty ranges
A percentage of the tax lost, set by your behaviour and by whether you came forward before HMRC found it. In a campaign disclosure you work the penalty out yourself, and where you took reasonable care there is none.
Careless
Unprompted 0 to 30%; prompted 15 to 30%.
Deliberate
Unprompted 20 to 70%; prompted 35 to 70%.
Deliberate and concealed
Unprompted 30 to 100%; prompted 50 to 100%.
Never told HMRC about the income
Failure to notify, not deliberate: unprompted 0 to 30% within 12 months of the tax being due, 10 to 30% after that; prompted 10 to 30%, or 20 to 30%.
Income or property abroad
Higher ranges apply to offshore income, up to 200%.
Left a long time
Where the tax went unpaid for a significant period, normally over 3 years, HMRC is unlikely to reduce the penalty by more than 10 points above the minimum.
Sources: HMRC factsheet CC/FS7a (opens in a new tab) and HMRC factsheet CC/FS11 (opens in a new tab) and HMRC, Let Property Campaign: your guide to making a disclosure (updated 6 April 2026) (opens in a new tab).
After the disclosure: records that keep it right
To keep rental income right after a Let Property Campaign disclosure, record each rent as it arrives and each cost with its receipt, against its property and tax year. The next return then starts from figures that are already right, and so do the quarterly updates when Making Tax Digital reaches you. Keeping the records of the let in one place is most of the work.
Rent recorded as it arrives
Rent you mark paid, or collected by Direct Debit, is posted as income on its date, against the property and the tax year it belongs to.
Every cost with its receipt
Photograph a receipt and it becomes a draft expense to check, or add an entry by hand. Costs sit in HMRC’s own categories, each on its property.
The SA105 figures at the year end
The Tax pack turns each year’s entries into the boxes of the property pages, for your return or your accountant, on paid plans. The guide to your first Self Assessment as a landlord covers registering and the deadlines.
Making Tax Digital from the same records
From 6 April 2027 it applies where your property and self-employment income on the 2025 to 2026 return was over £30,000, and the guide to the April 2027 threshold explains who that reaches. On paid plans the quarterly updates are worked out from the same entries.

This is general information from HMRC’s guidance, not tax advice. The rental income tax calculator estimates the tax on a year’s rental profit, and if your homes are owned by a company, company and personal properties sets out how the two are kept apart.
Settle the past once. Keep the records from now on.
Rent and costs by property and tax year, the SA105 figures and Making Tax Digital on paid plans, from £7.99 a month.

